🏛️ The Foundations of Fiscal Constitutionalism
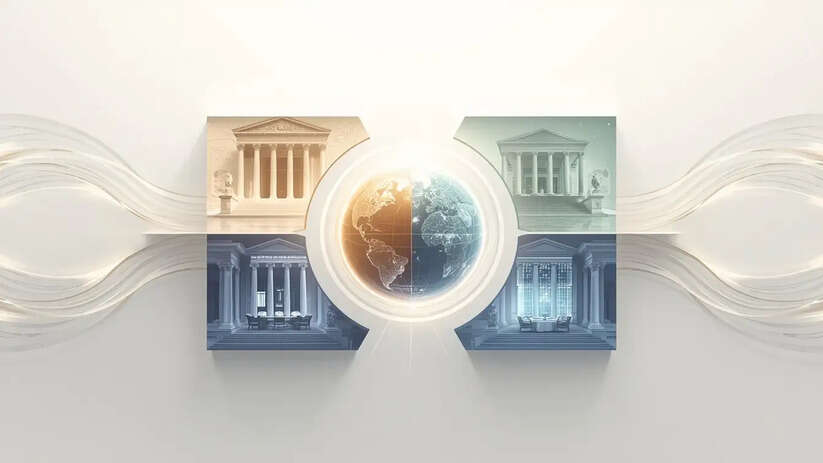
- The Westminster Face (Parliamentary): Employs deep forensic diagnostics and legislative reporting but faces operational vulnerability through Enforcement Paralysis.
- The Civil-Law Face (Court-of-Accounts): Acts as an Accountant Magistrate with high-velocity asset recovery powers, though vulnerable to Due Process Deficits.
- The Collegial Face (Board/Commission): Serves as an unshakeable Committee Shield of absolute neutrality, structurally exposed to Legislative Stalling.
- The Executive-Centred Face (Administrative): Delivers lightning-fast, real-time Concurrent Compliance but remains vulnerable to Executive Capture.
- The Unified Remedy: Integrates the predictive path-tracking memory of the GAJ Elephant with the deep, judicially backed enforcement of the JCB Bulldozer.
Public financial auditing across the world is a continuous, high-stakes wrestling match between the independent guardians who watch the money and the sovereign authorities who hold executive power. If we look past the dry landscape of traditional administrative text and isolate the raw structural choices of global public law, every single national oversight framework on Earth reduces to one of four foundational architectures. These conceptual configurations-the Westminster Face, the Civil-Law Face, the Collegial Face, and the Executive-Centred Face-operate as distinct institutional lenses, each hardcoding a unique method for extracting financial data, formulating institutional decisions, and enforcing structural compliance across a nation’s public treasury.
The Westminster Parliamentary Face, active in jurisdictions like the United Kingdom, the United States, and India, functions as a monocratic, single-headed watchdog that relies on advanced forensic analytics to expose material irregularities. This model possesses extraordinary diagnostic capabilities to trace historical data, dumping massive scam reports directly onto the tables of legislative committees to achieve democratic exposure. However, this configuration remains structurally vulnerable to enforcement paralysis, acting as an analytical sentinel that can bark loudly through its public reports but lacks the inherent legal teeth to execute penalties, leaving its findings exposed to being politically buried by a ruling legislative majority.
The Civil-Law Court-of-Accounts Face completely reverses this dynamic by transforming the external auditor into an Accountant Magistrate who swaps the calculator for a judicial gavel. In nations like France, Italy, and Brazil, these audit bodies operate as specialized constitutional courts staffed by independent judicial magistrates who possess the direct enforcement velocity to freeze private bank accounts and force negligent administrators to pay for public losses out of their own pockets. The systemic vulnerability here lies in due process deficits; because a single magisterial body operates as the investigator, prosecutor, and judge simultaneously, it frequently triggers intense legal friction regarding civil liberties and the right to an impartial tribunal.
The Collegial Audit Jurisprudence Face, utilized by countries like Germany and Japan, completely rejects the single-headed boss design, choosing instead to place all decision-making authority within a multi-member Board or Commission. This model serves as an unshakeable committee shield, providing absolute institutional neutrality because no single individual can be bullied, bought, or politically targeted by an aggressive executive. The structural bottleneck of this face is legislative stalling, where deep political polarization inside a gridlocked parliament can leave critical board seats vacant for years, effectively crippling the commission's capacity and leaving the public purse unmonitored.
The Executive-Centred Audit Face operates as an integrated administrative inside guard, positioned directly within the central executive apparatus as seen in configurations like China and Saudi Arabia. This face leverages real-time digital infrastructure and concurrent testing to catch accounting anomalies and freeze assets instantly within the bureaucracy before capital can leak out. While exceptionally brutal and fast at wiping out regional non-compliance and low-level corruption, this model is inherently vulnerable to total executive capture, as it lacks the independent constitutional insulation to execute uncompromised performance checks at the highest levels of political power.
Ultimately, these four faces are rarely static points on a governance map, as sovereign states frequently cross-pollinate their features or undergo institutional drift over time as their domestic legal frameworks evolve. True financial constitutionalism is achieved not by choosing a single face, but by applying Global Audit Jurisprudence (GAJ) to balance these variations, pairing the wise tracking memory of the analytical elephant with the raw mechanical power of a judicially backed bulldozer via the Jurisprudential Capability Building Program (JCBP). By ensuring that the technical findings of the auditor are matched by the immediate, binding enforcement of a strong higher judiciary, this unified framework secures the integrity of the public trust while fully preserving structural due process across all global governance grids.